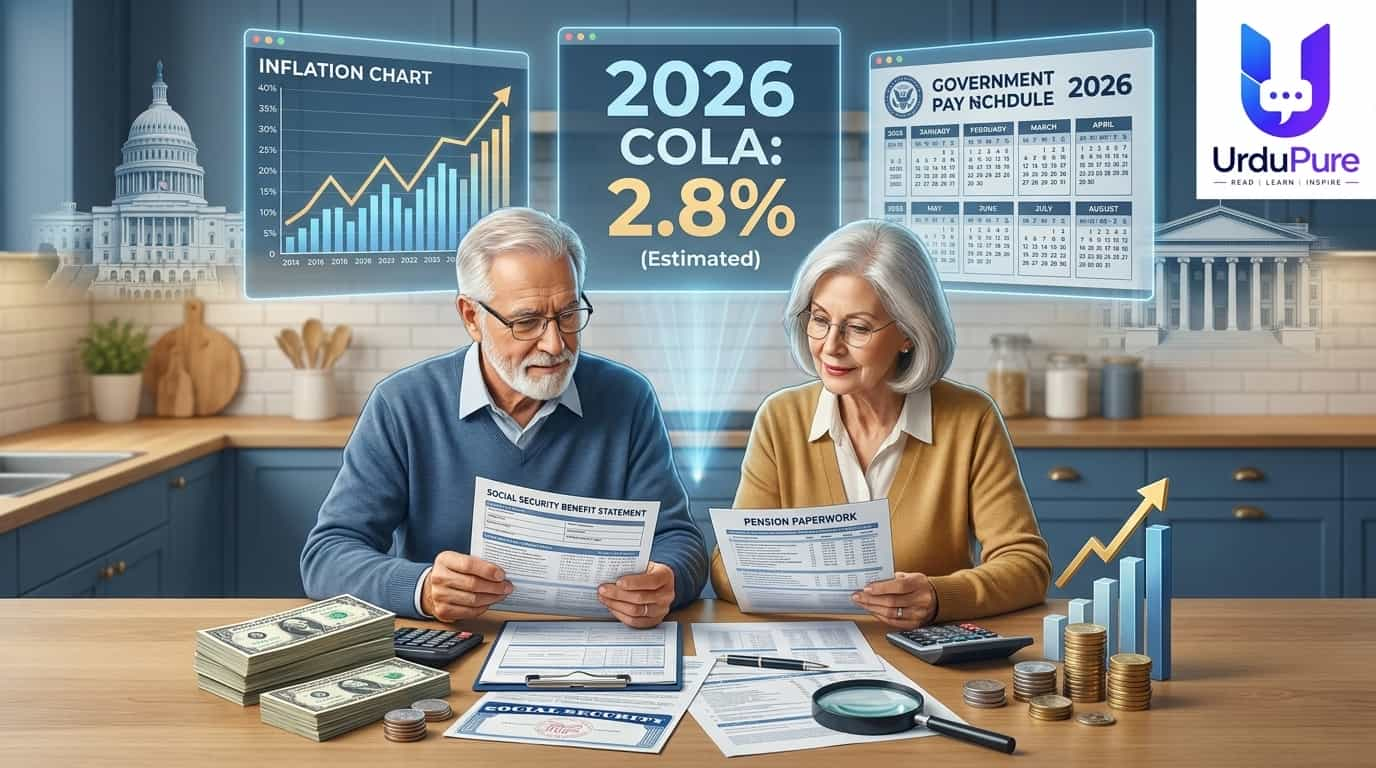
2026 Social Security COLA: What the Cost-of-Living Adjustment Means for Your Benefits
2026 Social Security COLA Projection: What Every Retiree and Near-Retiree Needs to Know
For the more than 70 million Americans who receive Social Security benefits — whether through retirement, disability, or survivor benefits — one of the most important financial events of every year is the announcement of the Cost-of-Living Adjustment (COLA). The COLA determines how much Social Security payments will increase the following year, and its size has enormous real-world implications for the financial wellbeing of tens of millions of households.
In 2026, the Social Security COLA projection is a topic of intense interest — both because of the recent history of elevated inflation and subsequent COLA increases, and because of the ongoing policy debates around Social Security's long-term financial health. This comprehensive guide covers everything you need to know: how the COLA is calculated, what the 2026 projection looks like, when and how the adjustment will appear in your benefits, and what steps you can take to maximize your Social Security income.
What Is the Social Security COLA? The Basics Explained
The Purpose of the Cost-of-Living Adjustment
The Cost-of-Living Adjustment (COLA) is an annual increase to Social Security and Supplemental Security Income (SSI) benefits designed to help recipients maintain their purchasing power as prices rise due to inflation. Without regular COLA increases, the fixed dollar amounts of Social Security checks would buy progressively less over time as the cost of goods and services increases — eroding the real value of benefits that millions of Americans depend on for financial survival.
The COLA mechanism was permanently established by law in 1975, removing the need for Congress to pass special legislation every time benefits needed to increase to keep pace with inflation. Before 1975, benefit increases required separate acts of Congress — a politically uncertain process that could leave recipients without needed adjustments. The automatic COLA system ensures that increases happen reliably and in proportion to actual inflation.
How the COLA Is Calculated: The CPI-W
The Social Security COLA is calculated using a specific inflation measure: the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), published by the Bureau of Labor Statistics (BLS). This is a slight variant of the more commonly discussed Consumer Price Index for All Urban Consumers (CPI-U), with a different weighting that gives more emphasis to the spending patterns of wage and clerical workers.
The calculation works as follows: The Social Security Administration (SSA) compares the average CPI-W for the third quarter of the current year (July, August, and September) to the average CPI-W for the third quarter of the prior year (or the last year in which a COLA was determined, if there was no adjustment). The percentage difference between these two averages becomes the COLA for the following year.
Example: If the average CPI-W in Q3 of the current year is 5% higher than in Q3 of the prior year, Social Security benefits will increase by 5% beginning in January of the following year.
The COLA History: Recent Years in Context
The Inflation Shock and Record COLAs
To understand the 2026 COLA projection, it helps to understand the recent history:
2022 COLA: 5.9% — The largest COLA in 40 years at the time of announcement, reflecting the inflation surge that began in 2021 as the economy reopened from pandemic shutdowns.
2023 COLA: 8.7% — The largest COLA since 1981, reflecting the peak of the post-pandemic inflation wave. For a retiree receiving $1,500/month, this represented an additional $130.50 per month — or over $1,566 per year.
2024 COLA: 3.2% — As inflation began to moderate, the COLA came down from its historic highs but remained well above the pre-pandemic baseline.
2025 COLA: 2.5% — Further moderation, reflecting the Federal Reserve's successful (if painful) campaign to bring inflation closer to its 2% target.
What the History Tells Us
The COLA history of the past several years tells a clear story: a period of extraordinary inflation produced historic benefit increases, and as inflation has moderated, COLA adjustments have come down toward more historically typical levels. Whether this trend continues, or whether new inflationary pressures — from tariffs, supply chain disruption, or other sources — push inflation (and thus COLA) higher again, is the central variable in 2026 COLA projections.
2026 Social Security COLA Projection: What the Numbers Say
The Projection Methodology
Because the COLA is officially determined using Q3 CPI-W data (released in October), formal projections for the 2026 COLA are based on the trajectory of inflation data through the period leading up to that determination. Economic analysts, advocacy organizations like the Senior Citizens League (TSCL), and financial media closely track monthly CPI-W releases and project the COLA based on current trends.
These projections are educated estimates — the actual COLA is not known until the official announcement in mid-October of each year, after September's CPI-W data is released.
Current 2026 COLA Projections
Based on the inflation data available through early 2026, analysts have been projecting a 2026 Social Security COLA in the range of approximately 2.3% to 3.1%, with most estimates clustering in the 2.5–2.7% range.
This range reflects:
Moderating Underlying Inflation: Core inflation — which excludes the volatile food and energy categories — has been gradually moving toward the Federal Reserve's 2% target, pulling the overall CPI-W trajectory down from its peaks.
Tariff-Related Upside Risk: The broad tariffs imposed by the Trump administration on Chinese and other imported goods carry the risk of pushing consumer prices higher — an upside risk to inflation (and thus to the COLA) that analysts are watching carefully. If tariff-driven price increases show up meaningfully in the CPI-W data through Q3, the actual COLA could come in at the higher end of projections or above.
Housing Costs: Shelter costs — rents and owner-equivalent rent — remain elevated and are a significant component of the CPI-W. The persistence of high housing costs has kept overall inflation somewhat above where it would otherwise be, supporting a COLA that remains above the 2% floor.
What a 2.5% COLA Means in Dollar Terms
To make the projection concrete, here is what a 2.5% COLA would mean for recipients at various benefit levels:
Monthly Benefit Dollar Increase New Monthly Benefit Annual Additional Income $1,000 +$25.00 $1,025 +$300 $1,500 +$37.50 $1,537.50 +$450 $1,800 +$45.00 $1,845 +$540 $2,000 +$50.00 $2,050 +$600 $2,500 +$62.50 $2,562.50 +$750 $3,000 +$75.00 $3,075 +$900
The average Social Security retirement benefit as of 2025 was approximately $1,900 per month, meaning the average recipient would see an increase of roughly $47.50 per month, or about $570 per year, under a 2.5% COLA.
When Will the 2026 COLA Be Announced and Take Effect?
The Official Announcement Timeline
The official 2026 Social Security COLA will be announced by the Social Security Administration in mid-October 2026, once the September CPI-W data has been published by the Bureau of Labor Statistics. This typically happens during the second week of October.
The announcement is widely reported in financial media and communicated directly to Social Security recipients through SSA channels.
When Will You See the Increase in Your Payment?
The COLA increase takes effect with benefits payable in January 2027 (reflecting the 2026 COLA determination). Social Security payments are paid the month after they are earned, so:
Payments received in January 2027 will reflect the 2026 COLA increase
For most recipients, this means the first increased payment will arrive in January or early February 2027, depending on their payment schedule
SSI recipients typically see their COLA increase with their December payment, which is paid in advance of January.
Your Personal COLA Notice
The Social Security Administration sends personalized COLA notices to every recipient, detailing their specific new benefit amount. These notices are typically mailed in December and are also available through the my Social Security online portal (ssa.gov/myaccount) for those who have created an account.
Creating a my Social Security account is strongly recommended for all current and near-future recipients — it provides access to benefit statements, earnings history, COLA notices, and other important account information.
The Medicare Premium Factor: The "Hold Harmless" Provision
What Is the Hold Harmless Provision?
One important nuance in how the COLA affects your actual take-home benefit involves Medicare Part B premiums, which are typically deducted directly from Social Security payments.
The "hold harmless" provision of Social Security law protects most Medicare beneficiaries from having their net Social Security benefit decrease due to Medicare Part B premium increases. Specifically, the law states that the Medicare Part B premium increase cannot exceed the dollar amount of a recipient's COLA increase.
In practical terms: if your Social Security benefit increases by $45/month due to the COLA, but Medicare Part B premiums rise by $10/month, your net benefit increase would be $35/month. The hold harmless provision ensures you always at least break even — your check cannot go down because of premium increases (with some exceptions for higher-income beneficiaries and new enrollees).
2026 Medicare Part B Premium Projections
Medicare Part B premiums for 2026 are projected to increase modestly from the 2025 level, reflecting healthcare cost inflation and the actuarial adjustments made by the Centers for Medicare & Medicaid Services (CMS). The specific premium increase will be announced alongside or shortly after the COLA announcement in October 2026.
Understanding both the COLA increase AND the Medicare premium change is essential for calculating your actual net benefit change for 2027.
Is the CPI-W the Right Measure for Seniors? The CPI-E Debate
The Case for a Different Index
One of the longstanding critiques of the Social Security COLA calculation is that the CPI-W — which measures the spending patterns of urban wage earners — may not accurately reflect the actual cost-of-living experience of older Americans on fixed incomes.
Seniors spend their income differently from working-age wage earners. Specifically, they spend a significantly higher proportion of their income on:
Healthcare: Including Medicare premiums, prescription drugs, and out-of-pocket medical costs — categories that have historically experienced inflation well above the overall CPI
Housing: Particularly for those who rent or live in assisted or nursing care facilities
They spend a smaller proportion on categories like transportation and certain consumer electronics where prices have been flat or declining.
The CPI-E (Consumer Price Index for the Elderly) — an experimental index developed by the Bureau of Labor Statistics — has historically shown that true inflation for older Americans runs somewhat higher than the CPI-W suggests. Advocates argue that using the CPI-E instead would produce more accurate (and higher) COLA adjustments that better protect seniors' purchasing power.
The Legislative Status
Bills to switch the Social Security COLA calculation from the CPI-W to the CPI-E have been introduced in Congress multiple times, with support from senior advocacy organizations. However, the change has not yet been enacted into law — partly because it would increase Social Security expenditures, and partly because the broader debate about Social Security's long-term solvency makes any individual change difficult to advance in isolation.
Social Security's Long-Term Financial Picture
The Trust Fund and Projected Depletion
The ongoing policy debate about Social Security cannot be separated from the program's long-term financial picture. The Social Security trustees' most recent annual report projects that the Old-Age and Survivors Insurance (OASI) Trust Fund — the fund from which retirement and survivor benefits are paid — will be depleted in the early-to-mid 2030s if no legislative changes are made.
Depletion of the trust fund would not mean Social Security stops paying benefits — it would mean that ongoing payroll tax revenues would only be sufficient to pay approximately 75–80% of scheduled benefits. This is a significant and serious challenge that Congress will need to address through some combination of:
Benefit adjustments (such as raising the full retirement age or changing the COLA calculation formula)
Revenue increases (such as raising or eliminating the Social Security payroll tax cap)
A combination of the above
Most analysts agree that the most equitable and least disruptive solution involves acting sooner rather than later — the longer Congress waits, the more dramatic the eventual adjustments need to be.
What This Means for Current and Future Retirees
For current retirees, the most important message is that Social Security benefits are very unlikely to be cut significantly in the near term — the political reality is that any changes affecting current recipients would be enormously difficult to pass. Most reform proposals protect current beneficiaries while making adjustments for future retirees.
For near-retirees and younger workers, the long-term picture underscores the importance of personal retirement savings — 401(k)s, IRAs, and other vehicles — as a complement to Social Security rather than a sole source of retirement income. Depending entirely on Social Security in a future where benefits may be modestly reduced from current projections is a financially risky strategy.
How to Maximize Your Social Security Benefits
The Power of Delayed Claiming
One of the most impactful decisions any Social Security recipient makes is when to claim benefits. The choices are significant:
Claiming at 62 (the earliest possible age): Benefits are permanently reduced by up to 30% compared to claiming at full retirement age
Claiming at Full Retirement Age (FRA) (currently 67 for those born after 1960): You receive your full primary insurance amount
Delaying to age 70: Benefits increase by 8% per year for each year you delay past FRA — a 24% increase over claiming at 67
For someone with average life expectancy or better, delaying Social Security claiming until 70 is often the mathematically superior strategy — providing higher lifetime benefits and better protection against longevity risk (the risk of outliving your savings).
Spousal and Survivor Benefits
Married couples have access to Social Security strategies — including spousal benefits (up to 50% of the higher earner's benefit) and survivor benefits (up to 100% of the deceased spouse's benefit) — that can significantly optimize total household lifetime Social Security income. Working with a qualified financial advisor who specializes in Social Security claiming strategies is valuable for married couples approaching retirement.
Earnings and the Earnings Test
If you claim Social Security before full retirement age and continue working, your benefits may be temporarily reduced if your earnings exceed certain thresholds. Understanding the earnings test — and how any withheld benefits are credited back to you after you reach FRA — is important for workers who plan to continue earning income while receiving early Social Security.
Frequently Asked Questions About the 2026 Social Security COLA
Q: When will the 2026 Social Security COLA be announced?
A: The official 2026 COLA announcement will be made by the Social Security Administration in mid-October 2026, after September's CPI-W data is published.
Q: When will the 2026 COLA increase appear in my payment?
A: The COLA takes effect with January 2027 payments. SSI recipients typically see the increase with their December 2026 payment.
Q: What is the projected 2026 Social Security COLA?
A: Early projections estimate the 2026 COLA at approximately 2.3% to 3.1%, with most estimates in the 2.5–2.7% range. The final number depends on Q3 2026 CPI-W data.
Q: Does the COLA affect Medicare premiums?
A: Medicare Part B premiums are deducted from Social Security payments. The "hold harmless" provision protects most recipients from having their net benefit decrease due to premium increases.
Q: Is Social Security going broke?
A: Social Security faces long-term funding challenges, with the trust fund projected to be depleted in the early-to-mid 2030s without legislative action. This would not eliminate benefits but could reduce them to approximately 75–80% of scheduled amounts without reform.
Q: How can I see my projected Social Security benefit?
A: Create a free my Social Security account at ssa.gov/myaccount to view your earnings record, estimated future benefits at various claiming ages, and official COLA notices.
For authoritative information on Social Security benefits and COLA updates, visit the official Social Security Administration website at ssa.gov or contact SSA directly at 1-800-772-1213. 2026 Social Security COLA, Social Security COLA 2026, Social Security cost of living adjustment 2026, Social Security increase 2026, COLA projection 2026, Social Security benefits 2026, how much will Social Security increase 2026, Social Security COLA calculation, when is COLA announced, Medicare premium 2026
Discussion
Comments
Approved comments are published after moderation to keep discussion useful and spam-free.
No comments yet. Start the discussion below.