Best High-Yield Savings Accounts of 2026 (Ranked by APY)
Interest rates are still historically favourable — but most people are leaving hundreds of pounds or dollars on the table in low-rate accounts. Here are the best-paying savings accounts available right now, ranked and honestly reviewed.
The Savings Rate Gap Is Costing You Real Money
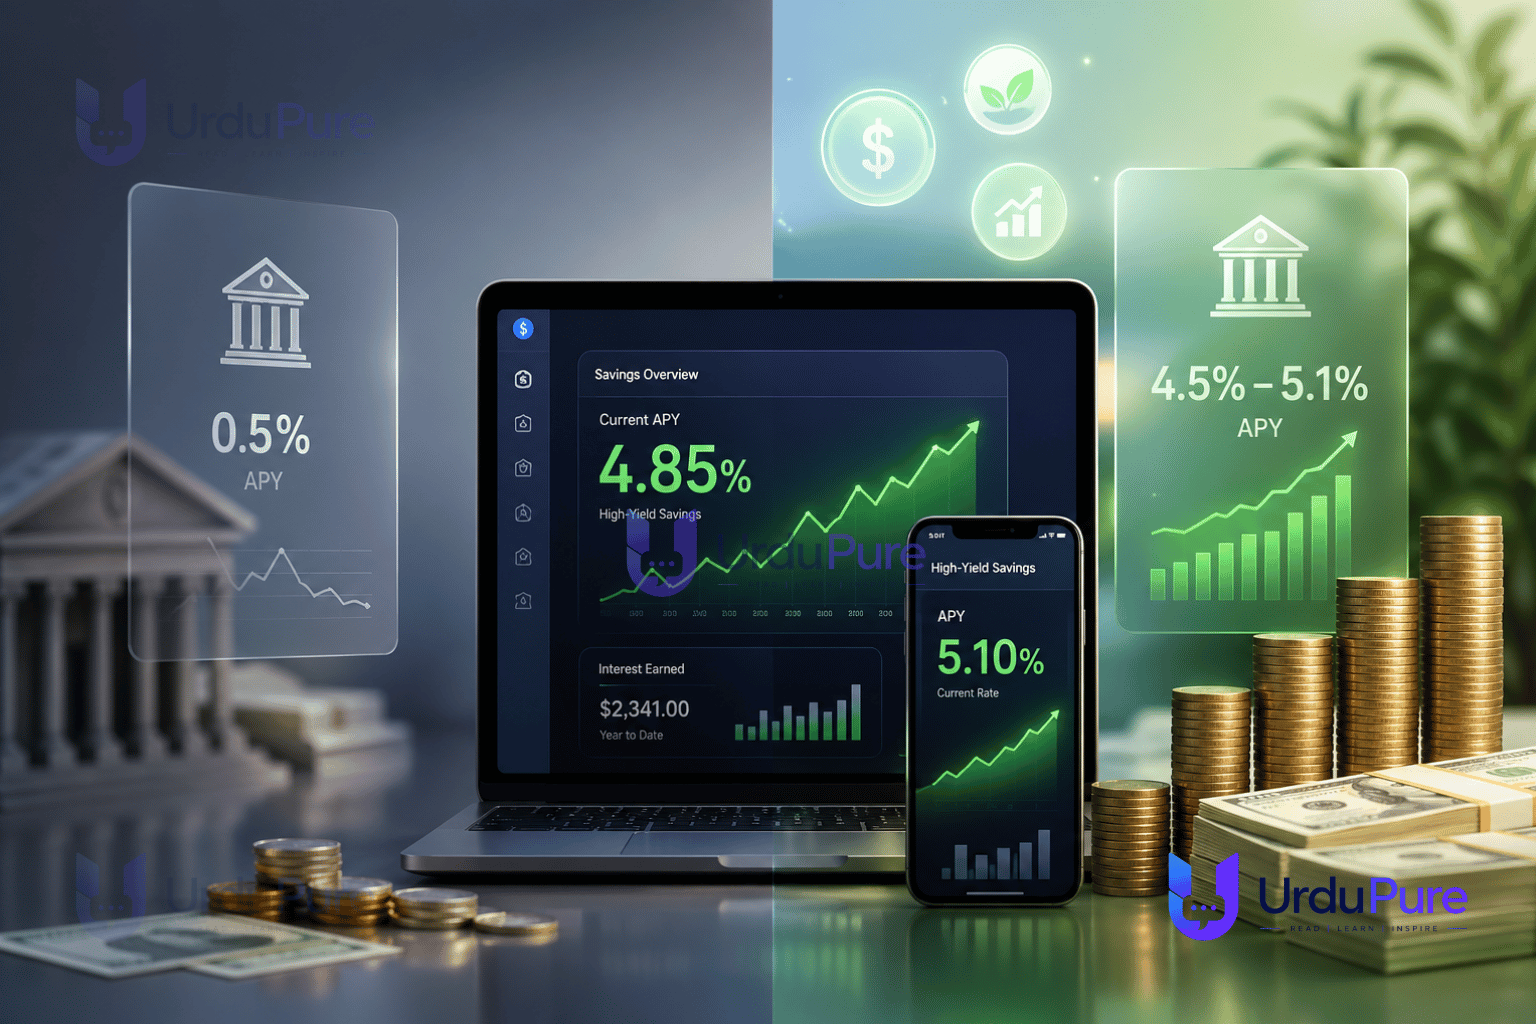
The average traditional bank savings account in the US pays just 0.46% APY. The average in the UK sits at a similarly unimpressive 0.5–1% for standard instant-access accounts at the high street banks. Meanwhile, the best high-yield savings accounts in both countries are paying 4.5–5.1% — more than ten times as much.
On a $10,000 balance, that difference amounts to roughly $460 in missed interest per year. On $50,000, it's over $2,300. Simply moving your savings to the right account — a process that takes about 15 minutes — is one of the highest-return, zero-risk financial moves available to anyone in 2026.
This guide ranks the best high-yield savings accounts available to US and UK savers right now, explains what to look for beyond the headline rate, and tells you exactly how to switch without disrupting your finances.
What Is a High-Yield Savings Account?
A high-yield savings account (HYSA) is a savings account — typically offered by online banks or digital financial institutions — that pays significantly more interest than traditional bank accounts. The higher rates are possible because online banks operate with lower overheads than high street banks: no branch network, fewer staff, and leaner infrastructure.
In the US, HYSAs are typically FDIC-insured up to $250,000 per depositor, making them exactly as safe as a standard bank account. In the UK, accounts covered by the Financial Services Compensation Scheme (FSCS) protect up to £85,000 per person per institution.
The only meaningful trade-off with most HYSAs versus traditional savings accounts is that they're primarily online or app-based. If you need to walk into a branch, these are not the accounts for you. For everyone else, the interest rate premium is straightforward to capture.
The Best High-Yield Savings Accounts in the US — 2026 Rankings
1. SoFi High-Yield Savings — Up to 5.10% APY
SoFi currently offers one of the highest rates available in the US, with up to 5.10% APY when you set up direct deposit. Without direct deposit, the rate drops to 1.20% — so this account rewards customers who use it as their primary banking relationship. No account fees, no minimum balance, and FDIC-insured up to $2 million through its partner bank programme make this a standout option for those willing to consolidate their banking.
Best for: People happy to use SoFi as their main bank account.
Watch out for: The rate difference between direct deposit and non-direct deposit customers is significant — check which tier applies to you.
2. Marcus by Goldman Sachs — 4.90% APY
Marcus has long been the reliable benchmark for no-nonsense high-yield savings in the US. No fees, no minimum balance, easy transfers to any external account, and the security of Goldman Sachs backing make it consistently one of the most recommended options. The rate is competitive without being the absolute highest, but the simplicity and trustworthiness of the product are hard to beat for straightforward savers.
Best for: Savers who want a clean, simple, reliable account with no strings attached.
Watch out for: No ATM access and no checking account option — this is purely a savings vehicle.
3. Ally Bank — 4.75% APY
Ally is consistently rated among the best online banks in the US for its combination of competitive rates, excellent customer service, and a genuinely useful suite of account features. The savings account includes "savings buckets" — virtual sub-accounts that let you organise money by goal without opening multiple accounts. The rate is slightly below the very top options but the overall banking experience is arguably the best available online.
Best for: People who want the best overall digital banking experience alongside a strong savings rate.
Watch out for: Rate is slightly lower than top competitors — if maximising APY is the only goal, there are better options.
4. Discover Online Savings — 4.70% APY
Discover's online savings account combines a strong rate with the reliability of a well-established brand and genuinely good customer service. No minimum balance, no monthly fees, and 24/7 US-based customer support. The Discover ecosystem integrates well if you also carry a Discover credit card, making it a natural choice for existing Discover customers.
Best for: Existing Discover customers or those who value strong customer service.
Watch out for: Rate is competitive but not market-leading — periodically check whether switching is worthwhile.
5. Bread Financial High-Yield Savings — 5.05% APY
Bread Financial (formerly Comenity Bank) offers one of the highest flat rates available — 5.05% with no conditions attached, no direct deposit requirement, and no minimum balance. Less well-known than the other options on this list, but FDIC-insured and straightforward. For savers who simply want the highest rate with the fewest strings, Bread Financial is worth serious consideration.
Best for: Pure rate maximisers who want no conditions on their high rate.
Watch out for: Less developed app and digital experience than Marcus or Ally.
The Best High-Yield Savings Accounts in the UK — 2026 Rankings
1. Chase UK Easy Saver — 4.90% AER
Chase UK has rapidly become one of the most popular digital banking options in the UK since its launch, and its savings rate reflects its determination to win market share. The Easy Saver account pays 4.90% AER with instant access — no notice period, no lock-in, and money available any time. Combined with the Chase current account, which offers 1% cashback on debit card spending, this is arguably the strongest overall digital banking package available to UK customers in 2026.
Best for: UK savers who want a complete digital banking relationship with competitive rates.
Watch out for: Rate has been variable since launch — set a calendar reminder to check quarterly.
2. Trading 212 Cash ISA — 5.10% AER (tax-free)
Trading 212's Cash ISA deserves special mention because it combines a market-leading rate with the significant tax advantage of the ISA wrapper. Interest earned in an ISA is completely free of income tax, which makes a meaningful difference for higher-rate taxpayers. At 5.10% AER with instant access and FSCS protection, this is the strongest combination of rate and tax efficiency available to UK savers in 2026.
Best for: Higher-rate taxpayers and anyone who hasn't yet used their £20,000 annual ISA allowance.
Watch out for: Trading 212 is primarily an investment platform — the Cash ISA is a newer product and lacks the banking heritage of traditional providers.
3. Chip — 4.84% AER
Chip has evolved from its origins as an automated savings app into a fully-fledged savings platform with one of the most competitive easy-access rates in the UK market. The app experience is excellent, the rate is strong, and the autosave features — which analyse your spending and move small amounts into savings automatically — are genuinely useful for people who struggle to save consistently.
Best for: People who want behavioural savings tools alongside a competitive rate.
Watch out for: FSCS protection is provided through a partner bank — worth checking the current arrangement.
4. Monzo Savings Pot (Flexible) — 4.75% AER
Monzo's flexible savings pot, powered by partner banks, offers a competitive rate with the convenience of being embedded directly in the Monzo app — which millions of UK users already use as their main current account. The ability to move money between current account and savings pot instantly, with no separate login or transfer wait, makes this the most frictionless savings option for existing Monzo customers.
Best for: Existing Monzo users who want zero-friction savings management.
Watch out for: Rate depends on the underlying partner bank and can change — check the Monzo app for the current rate.
5. NS&I Premium Bonds — 4.40% prize fund rate (tax-free)
Premium Bonds deserve inclusion in any UK savings ranking as a unique proposition: instead of paying fixed interest, NS&I enters all bond holders into a monthly prize draw. The current prize fund rate is equivalent to 4.40% AER — entirely tax-free and backed by the UK government (the only savings product with 100% government guarantee beyond the FSCS limit). For higher-rate taxpayers, the tax-free equivalent yield is considerably more attractive, and the lottery element adds interest for those who enjoy it.
Best for: Higher-rate taxpayers, those with savings above the FSCS limit seeking full government backing, and people who enjoy the prize element.
Watch out for: Returns are probabilistic not guaranteed — statistically, the effective rate is close to 4.40% but individual returns vary.
Beyond the Rate: What Else to Consider
FDIC / FSCS Protection Limits
In the US, FDIC insurance covers $250,000 per depositor per institution. If your savings exceed this — congratulations — spread the excess across multiple FDIC-insured institutions. In the UK, FSCS protection covers £85,000 per person per institution (£170,000 for joint accounts).
Rate Stability vs Introductory Offers
Some accounts offer temporarily inflated rates to attract new customers before reverting to lower standard rates. Always check whether the advertised rate is the ongoing standard rate or a fixed-term introductory offer. Marcus and Ally are known for stable, competitive rates over time. Others are more variable.
Access and Withdrawal Terms
Most high-yield savings accounts offer instant or near-instant access to your money. Some notice accounts (which require 30, 60, or 90 days' notice before withdrawal) offer slightly higher rates in exchange for reduced flexibility. Unless you have money you genuinely won't need for months, the convenience of instant access is usually worth the small rate difference.
Tax Considerations
In the US, interest from savings accounts is taxable as ordinary income. Keep this in mind if your total interest income pushes you into a higher tax bracket. In the UK, basic rate taxpayers have a £1,000 Personal Savings Allowance (interest below this threshold is tax-free); higher rate taxpayers have a £500 allowance. Above these thresholds, the ISA wrapper becomes critically important.
How to Switch: A 15-Minute Guide
Choose your account from the options above based on your country, tax situation, and whether you want the very highest rate or the best overall banking experience.
Open the account online — most take 5–10 minutes. You'll need a form of ID (passport or driving licence) and your existing bank details.
Transfer your savings — initiate a transfer from your old savings account. Most transfers arrive within 1–3 business days.
Set up a standing order from your current account into the new savings account on payday. Automate your savings and remove the willpower requirement entirely.
Set a quarterly reminder to check rates. The high-yield savings market is competitive and rates shift — 10 minutes of attention every three months ensures you're never materially behind the best available rate.
The Bottom Line
There is no financial move available to the average saver in 2026 that delivers a better risk-adjusted return than moving money from a low-rate traditional bank account into a high-yield savings account. The process takes 15 minutes. The ongoing benefit — hundreds to thousands of pounds or dollars per year in additional interest, depending on your balance — is entirely passive and entirely guaranteed.
The best account is the one that matches your situation: country, tax bracket, banking preferences, and how much flexibility you need. But almost any account on this list is dramatically better than a standard high street savings account. Pick one, open it today, and let the interest do the work.
Disclaimer: Interest rates are accurate as of April 2026 and are subject to change. This article is for informational purposes only and does not constitute financial advice. Always verify current rates directly with the provider before opening an account.
best high yield savings accounts 2026, highest APY savings accounts, best savings accounts UK 2026, Marcus vs Ally vs SoFi, Chase UK savings rate, Trading 212 cash ISA, where to keep savings 2026, FSCS protected savings accounts, FDIC insured savings, easy access savings rates 2026
Discussion
Comments
Approved comments are published after moderation to keep discussion useful and spam-free.
No comments yet. Start the discussion below.