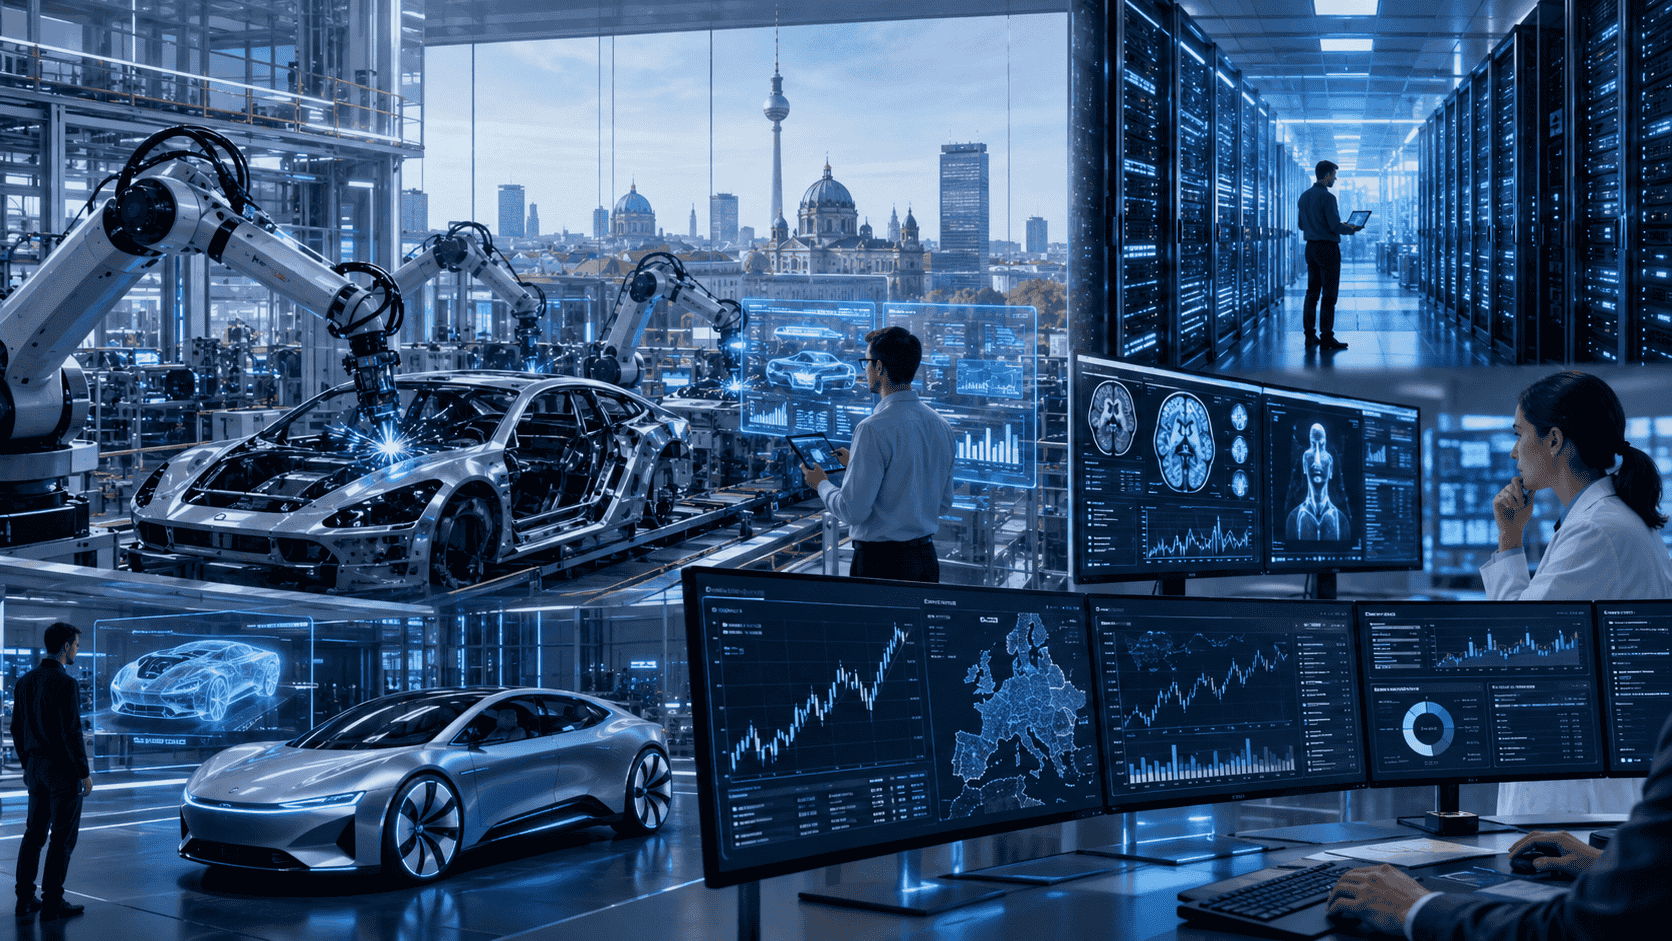
1. Executive Summary and 2026 Update Dashboard
Germany’s AI market has moved from strategic experimentation
to operational adoption. The 2024 edition correctly identified Germany’s
industrial base, engineering capability, enterprise software ecosystem and
strict trust culture as the market’s defining strengths. The main change in
2026 is speed: adoption is now broad enough to justify a stronger near-term
forecast, while regulation and compute capacity have become central
market-shaping forces rather than background issues.
|
Headline finding |
|
Signal |
Latest
reading |
Market
meaning |
|
Enterprise adoption |
ifo reports 54.5% of companies in Germany using AI in business
processes as of May 2026. |
AI has become mainstream, not just a large-enterprise pilot
topic. |
|
Industry adoption |
Manufacturing usage is reported at 58.7%, with services at
56.2%. |
Industrial AI is now a core productivity lever for
factories and exporters. |
|
Market size anchor |
GTAI cites USD 9.9bn domestic AI market size in 2025 and
USD 40.4bn forecast by 2031. |
The market trajectory is faster than the old 2024 base
case. |
|
Startup landscape |
appliedAI identifies 935 German AI startups in 2025, up 36%
year on year. |
Germany’s AI startup base is becoming broader and more
investable. |
|
Regulation |
The AI Act is fully applicable from 2 August 2026, with
exceptions and high-risk transition dates into 2027-2028. |
Compliance becomes a market in its own right. |
|
Infrastructure |
Germany plans to at least double data-center capacity and
quadruple AI processing capacity by 2030. |
Compute, energy and sovereignty become strategic
constraints and investment opportunities. |
|
European compute |
EU AI Factories and Gigafactories target access to
large-scale AI compute; Germany hosts JUPITER AI Factory. |
Public-private compute capacity can support startups, SMEs
and regulated sectors. |
Executive
conclusions
·
Germany is no longer an “AI
potential” market. It is an AI adoption market, with the largest upside in
industrial operations, enterprise software, regulated sectors, healthcare,
automotive, energy and customer-service automation.
·
The strongest near-term
commercial demand is not only model development. It is integration: data
engineering, AI governance, workflow redesign, MLOps, security, cloud
migration, hybrid deployment and training.
·
The German market rewards
trust, auditability and domain depth. Vendors that combine strong AI
performance with explainability, EU AI Act readiness, GDPR-sensitive
architecture and German-language reliability will have an advantage.
·
The biggest structural
bottlenecks are compute capacity, energy availability, scarce AI talent, slow
legacy integration, data readiness and compliance complexity.
·
AI sovereignty has moved
from a policy phrase to a procurement reality. Regulated customers will
increasingly ask where data is processed, who controls model infrastructure,
how systems are audited and whether vendors can survive regulatory scrutiny.
2. What
Changed Since the 2024 Edition
The uploaded 2024 report provided the right base architecture:
component segmentation, technology segmentation, deployment mode, organization
size, business functions, industry verticals, competitive landscape and
forecasts to 2035. This update preserves that structure but refreshes the
assumptions.
|
Area |
2024
edition position |
2026
updated reading |
|
AI adoption |
Large enterprises led; SMEs were slower and cautious. |
AI use has become mainstream across the economy; SMEs and
microbusinesses are catching up quickly, though maturity still varies. |
|
Generative AI |
Fast-growing but still moving from pilots to deployment. |
Enterprise copilots, customer-service agents, document
intelligence and code assistants are now operational budget lines. |
|
Regulation |
EU AI Act was a future compliance event. |
AI Act obligations are now active or imminent; compliance
tooling and governance services are strategic growth markets. |
|
Compute infrastructure |
Important but secondary to software and adoption. |
A first-order constraint and policy objective: data
centers, AI factories, HPC and energy efficiency are central to the market
outlook. |
|
Startup ecosystem |
Promising clusters in Berlin, Munich and Hamburg. |
Startup volume, venture attention and AI unicorn formation
accelerated; consolidation and cross-border alliances also increased. |
|
Services |
Strong but behind software in strategic attention. |
Revised upward because implementation work, governance,
integration and change management are absorbing major enterprise budgets. |
The prior base case of USD 57.2 billion by 2035 is now
conservative. This ebook’s updated base case of USD 74.8 billion assumes that
Germany sustains high AI adoption growth through 2031 and then moderates into a
mature, regulated, productivity-focused AI market. The bull case of USD 96.5
billion requires faster compute expansion, stronger SME adoption, robust
industrial AI ROI and lower regulatory friction. The bear case of USD 55.6
billion would occur if regulation, energy constraints, investment weakness or
integration failures slow the conversion of pilots into production.
3.
Updated Market Size and Forecast to 2035
The updated model uses the uploaded report as the 2024 baseline, adds the public 2025 market-size anchor from Germany Trade and Invest, and revises the 2026-2035 trajectory using current evidence on enterprise adoption, data-center policy, generative AI demand and implementation spending.
|
Year |
Bear
case |
Base
case |
Bull
case |
|
2024 |
7.9 |
8.4 |
8.9 |
|
2025 |
9.4 |
9.9 |
10.6 |
|
2026 |
11.3 |
12.5 |
13.8 |
|
2027 |
13.4 |
16.0 |
18.1 |
|
2028 |
15.9 |
20.2 |
23.8 |
|
2029 |
19.0 |
25.5 |
31.3 |
|
2030 |
22.7 |
32.0 |
41.0 |
|
2031 |
27.8 |
40.4 |
53.5 |
|
2032 |
33.9 |
48.3 |
64.5 |
|
2033 |
40.4 |
57.5 |
76.1 |
|
2034 |
47.6 |
66.1 |
87.2 |
|
2035 |
55.6 |
74.8 |
96.5 |
Base-case
forecast logic
·
2026-2031: faster growth as
AI becomes a normal enterprise software, automation and productivity budget
line.
·
2031-2035: growth moderates
as the market matures, compliance becomes standardized and AI shifts from
adoption to optimization.
·
Services share grows
because Germany’s AI value chain requires data readiness, legacy system
integration, regulatory documentation, staff enablement and operating-model
redesign.
·
Hardware remains
strategically important but volatile due to GPU supply, data-center energy
constraints, geopolitics and rapidly changing inference economics.
Updated component forecast
|
Component |
2024
original |
2026
updated estimate |
2035
updated forecast |
Strategic
implication |
|
Hardware |
USD 2.6bn |
USD 3.7bn |
USD 19.1bn |
Higher edge AI, GPU/HPC and data-center demand; procurement
risk remains high. |
|
Software |
USD 3.9bn |
USD 6.0bn |
USD 36.3bn |
Largest value pool as AI becomes embedded in ERP, CRM, HCM,
cybersecurity and vertical apps. |
|
Services |
USD 1.9bn |
USD 2.8bn |
USD 19.4bn |
Fastest revision upward because implementation, AI
governance, MLOps and compliance services are now critical. |
|
Total |
USD 8.4bn |
USD 12.5bn |
USD 74.8bn |
Base case revised upward from the 2024 edition due to
faster adoption and infrastructure policy. |
|
Sensitivity |
Upside
driver |
Downside
driver |
|
AI adoption |
SMEs and public sector move from trial to production. |
Pilots remain isolated and ROI is not measured. |
|
Regulation |
Clear standards reduce uncertainty and make trust a
competitive advantage. |
Compliance cost slows high-risk AI deployments. |
|
Compute |
Data-center and AI Factory capacity improves access for startups
and industry. |
GPU scarcity, power constraints or permitting delays limit
capacity. |
|
Talent |
Immigration, training and AI tooling expand applied AI
capacity. |
Shortage of data engineers, MLOps staff and AI governance
specialists persists. |
|
Macroeconomy |
Productivity pressure forces automation investment. |
Weak demand delays discretionary digital transformation
projects. |
4.1
Ecosystem position
Germany’s AI advantage remains distinctive: it is less
consumer-platform-driven than the United States and less centralized than
China. Its strongest market logic is the combination of industrial depth,
enterprise software, engineering know-how, applied research, regulated-sector
trust and export-oriented manufacturing. This creates strong demand for AI
systems that are robust, auditable and operationally embedded.
·
Research and transfer base:
DFKI, Fraunhofer institutes, Max Planck, Helmholtz, Cyber Valley, university AI
centers, Jülich and Munich/Berlin AI ecosystems.
·
Industrial base:
automotive, machinery, chemicals, electrical engineering, medical devices,
logistics and energy-intensive production.
·
Enterprise software base:
SAP ecosystem, Microsoft/Azure penetration, German cloud and integration
providers, and deep installed base of ERP and MES systems.
·
Trust advantage: strict
data culture and regulatory discipline can slow experimentation but also
strengthen trusted AI offerings for healthcare, finance, public sector and
industrial systems.
4.2
Policy and regulatory update
The EU AI Act is now central to Germany’s AI
commercialization model. It creates compliance costs but also creates clarity,
demand for governance products and a trust-based sales narrative. Prohibited AI
practices and AI literacy obligations applied from February 2025. Governance
rules and obligations for general-purpose AI models applied from August 2025.
The Act is fully applicable from 2 August 2026, while high-risk timelines
extend into 2027 and 2028 depending on category.
|
Compliance market insight |
|
AI
Act milestone |
Commercial
meaning for Germany |
|
2 February 2025: prohibited practices and AI literacy
obligations |
Companies need staff training, policy updates and controls
preventing banned uses. |
|
2 August 2025: GPAI governance and model-provider
obligations |
Foundation-model supply chains require documentation and
risk due diligence. |
|
2 August 2026: broad applicability |
AI governance shifts from best practice to legal operating
requirement. |
|
2 December 2027: selected high-risk areas |
Employment, education, biometrics, critical infrastructure
and public-sector AI need earlier readiness. |
|
2 August 2028: high-risk systems embedded in regulated
products |
Automotive, medical devices, machinery and other product-integrated
AI receive extended transition but must prepare early. |
Infrastructure is now a strategic pillar of the German AI
market. Germany’s 2026 plan to double domestic data-center capacity and quadruple
AI data processing capacity by 2030 shows that compute access has become a
national competitiveness concern. At the European level, AI Factories and AI
Gigafactories aim to create trusted, large-scale infrastructure that startups,
SMEs, industry and researchers can access.
·
The JUPITER AI Factory in
Jülich positions Germany inside the European AI compute network and supports
startups, SMEs, industry and cutting-edge research.
·
JUPITER is Europe’s first
exascale supercomputer and was ranked the fastest supercomputer in Europe and
fourth on the June 2025 TOP500 list.
·
EU AI Gigafactories are
designed around very large AI processor clusters, energy efficiency, supply
chains and advanced networking, with a EUR 20 billion InvestAI facility
supporting up to five gigafactories.
5.
Component Outlook: Hardware, Software and Services
5.1
Hardware
AI hardware in Germany is being pulled by four forces: cloud
and sovereign data-center expansion, HPC access for research and startups,
industrial edge AI, and automotive/robotics compute. The hardware market
remains exposed to global supply chains, especially GPUs, high-bandwidth
memory, advanced packaging and AI accelerator roadmaps. Germany has
semiconductor strengths in automotive, sensors and power electronics, but it remains
dependent on non-European suppliers for frontier AI training chips.
·
Near-term growth: GPU/HPC
clusters, AI servers, cooling, energy systems, edge gateways and industrial
inference devices.
·
Strategic bottlenecks:
power availability, grid connection time, land permitting, cooling,
procurement, export controls and supplier concentration.
·
Best-positioned use cases:
visual inspection, predictive maintenance, factory robotics, vehicle
perception, hospital imaging and grid optimization.
5.2
Software
Software remains the largest and most scalable value pool.
The strongest opportunities are not only horizontal AI platforms but also
embedded AI in enterprise applications and vertical systems. Germany’s
installed ERP, CRM, MES, PLM and industrial IoT base creates a large market for
AI that plugs into existing workflows rather than replacing them overnight.
·
Enterprise copilots:
Microsoft, SAP, Google and other platform vendors are embedding AI into office
productivity, ERP, analytics and customer workflows.
·
Vertical software:
healthcare imaging, automotive engineering, supply-chain intelligence,
industrial quality, legal document intelligence and financial risk tooling.
·
Model layer:
German-language quality, data residency, retrieval-augmented generation, secure
model access and domain fine-tuning are key buying criteria.
5.3
Services
Services are revised upward in this edition because German
AI adoption is bottlenecked less by awareness and more by operational
implementation. Enterprises need help with use-case selection, data readiness,
procurement, integration, governance, AI literacy, change management and
production operations.
·
High-margin advisory: AI
roadmaps, AI Act readiness, risk classification, governance operating models
and board-level AI strategy.
·
Technical implementation:
data pipelines, retrieval systems, API integration, MLOps, test harnesses,
cybersecurity and observability.
·
Managed services: ongoing
model monitoring, compliance reporting, AI helpdesks, prompt operations,
customer-service agent tuning and incident response.
6. Technology Outlook
|
Technology |
2026
estimate |
2035
forecast |
2026-2035
reading |
|
Machine learning / predictive AI |
USD 5.0bn |
USD 28.5bn |
Core engine behind forecasting, quality control, risk
scoring and personalization. |
|
NLP, generative AI and enterprise copilots |
USD 3.0bn |
USD 20.5bn |
Fastest commercial growth; German-language quality and
governance are decisive. |
|
Computer vision and physical AI |
USD 2.1bn |
USD 13.5bn |
Strategic in automotive, manufacturing, medical imaging, logistics
and robotics. |
|
Context-aware and agentic systems |
USD 2.4bn |
USD 12.3bn |
Rising from recommendation and IoT systems into autonomous
workflow orchestration. |
Traditional machine learning remains the workhorse of German
AI because it solves measurable business problems: forecast demand, detect
anomalies, optimize processes, classify risk and predict failures. In
industrial settings, ML remains more important than generic chatbots because it
directly influences uptime, energy consumption, quality and throughput.
6.2
Natural language processing and generative AI
NLP is the fastest-changing segment because large language
models have turned language into a general-purpose interface for enterprise
systems. German-language performance has improved significantly, making LLMs
useful for knowledge search, legal drafts, customer support, financial
documentation, technical manuals and multilingual export workflows. The next
phase is not only text generation but reliable task execution with retrieval,
workflows, permissions and auditability.
6.3
Computer vision and physical AI
Computer vision is strategically important because Germany’s
AI opportunity is deeply physical. Automotive perception, robot guidance,
defect detection, medical imaging and warehouse automation all depend on visual
understanding. Physical AI and embodied AI will connect vision, language,
robotics and controls in the second half of the forecast period.
6.4
Context-aware and agentic AI
Context-aware AI is moving from recommendation engines and
smart buildings into agentic systems that can interpret context and take
action. In Germany, agentic AI will develop most quickly in controlled
environments: customer service, procurement, maintenance workflows, commerce
operations, software engineering, finance operations and industrial
troubleshooting. The key requirement is bounded autonomy, not unrestricted
autonomy.
|
Agentic AI rule for Germany |
7.
Deployment Outlook: Cloud, Hybrid, Sovereign AI and AI Factories
Cloud remains the easiest path to AI adoption, but Germany’s
market is shifting toward a more nuanced deployment model. Regulated sectors
and industrial customers increasingly want hybrid architectures that combine
cloud scalability, on-premises control, edge inference and sovereign
data-management options.
|
Deployment
model |
Best-fit
customers |
2026-2035
outlook |
|
Public cloud AI |
Startups, digital-native firms, non-sensitive workloads,
productivity copilots |
Fastest route to experimentation and scale; constrained by
data residency and vendor lock-in concerns. |
|
Private cloud / sovereign cloud |
Government, finance, healthcare, critical infrastructure,
regulated industrial data |
Increasingly important as AI sovereignty becomes part of
procurement. |
|
Hybrid cloud |
Large enterprises with legacy systems and multiple
compliance zones |
Likely default architecture for German enterprise AI. |
|
Edge AI |
Factories, vehicles, hospitals, logistics, energy and smart
buildings |
High growth where latency, privacy, safety or connectivity
require local inference. |
|
HPC / AI Factory access |
Researchers, deep-tech startups, industrial consortia,
public-sector projects |
Strategic complement to hyperscalers; needs user-friendly
access and cloud-like tooling. |
·
BFSI: hybrid and
private-cloud deployments dominate sensitive risk, credit and compliance use
cases; public cloud grows for productivity and analytics.
·
Healthcare: patient data
privacy and medical-device rules favor controlled environments, but AI imaging
and documentation tools will expand quickly.
·
Automotive: cloud for
training and fleet analytics; edge for in-vehicle inference and safety-critical
functions.
·
Manufacturing: edge and
hybrid architectures are essential because factories need low latency,
equipment integration and high availability.
·
Public sector: sovereignty,
explainability and procurement compliance will shape slower but durable demand.
8. Organization Size Outlook
8.1
Large enterprises
Large enterprises remain the dominant spending group because
they have data, budgets, internal transformation teams and pressure to improve
productivity. The 2026 shift is that large companies are moving beyond
scattered pilots toward AI portfolio management. Boards increasingly want
dashboards showing which AI use cases are in production, what ROI they deliver,
what risks exist and what controls are in place.
8.2 SMEs
and Mittelstand
SMEs are the biggest long-term growth frontier. Adoption has
accelerated, but maturity remains uneven. Many firms can use AI through
packaged applications, low-code platforms and managed services rather than
building custom models. The best SME solutions will be simple, vertical,
affordable and integrated into existing workflows.
|
SME
barrier |
Practical
solution |
|
No internal AI team |
Managed AI services, low-code tools, vendor templates and
external implementation partners. |
|
Poor data readiness |
Start with data inventory, master data cleanup and small
use cases with measurable ROI. |
|
Fear of regulation |
Use AI Act readiness checklists, pre-classified vendor
documentation and human oversight. |
|
Budget uncertainty |
Begin with productivity use cases that pay back in less
than 12 months. |
|
Integration complexity |
Prefer APIs, connectors and phased deployment over full
system replacement. |
The rise of consumer-grade and low-cost AI tools creates a
new adoption layer among microbusinesses. The opportunity is less about custom
AI development and more about workflow acceleration: marketing content,
document drafting, invoicing support, customer communication, translation,
scheduling and research. This segment is price-sensitive but can scale through
SaaS and templates.
9.
Business Function Outlook
|
Function |
2026
priority |
Why
it matters in Germany |
|
Operations and supply chain |
Very high |
Directly linked to industrial competitiveness, energy use,
quality and export reliability. |
|
Marketing, sales and customer service |
Very high |
GenAI and voice agents show measurable ROI, especially in high-volume
service environments. |
|
Finance, risk and compliance |
High |
Banks and insurers need explainable, auditable AI under EU
and BaFin expectations. |
|
Security |
High |
AI helps detect attacks, but AI systems also expand the
attack surface and require governance. |
|
Human resources |
Medium-high |
Use cases are growing, but high-risk rules and employee
data protection require strict controls. |
|
Legal and contract operations |
Medium-high |
Document intelligence is attractive, but confidentiality,
accuracy and audit trails remain decisive. |
|
R&D and product development |
High |
Germany can combine AI with engineering, materials science,
chemicals, automotive and robotics. |
·
Productivity copilots:
internal knowledge search, meeting summaries, drafting, translation and code
generation.
·
Customer operations: AI
voice agents, chatbots, routing, complaint handling, claims intake and
multilingual support.
·
Industrial performance:
predictive maintenance, quality inspection, process optimization, energy
forecasting and digital twins.
·
Risk and compliance:
transaction monitoring, document review, AI governance, controls testing and
audit evidence management.
·
R&D acceleration:
materials discovery, simulation support, engineering documentation, test
generation and synthetic data.
10.
Industry Vertical Outlook
|
Industry
vertical |
2026
estimate |
2035
forecast |
Primary
AI spending themes |
|
Automotive and mobility |
USD 2.1bn |
USD 13.5bn |
Software-defined vehicles, ADAS, autonomous functions, manufacturing
and supply-chain AI. |
|
Manufacturing / Industrie 4.0 |
USD 1.9bn |
USD 12.5bn |
Predictive maintenance, visual quality, digital twins,
robotics and process optimization. |
|
BFSI |
USD 1.9bn |
USD 10.9bn |
Fraud, risk, compliance, customer service automation and
AI-assisted advisory. |
|
IT and telecommunications |
USD 1.6bn |
USD 9.4bn |
Cloud AI, network optimization, cybersecurity, software
engineering copilots. |
|
Healthcare |
USD 1.5bn |
USD 10.1bn |
Imaging, workflow automation, decision support, life
sciences and patient operations. |
|
Retail and e-commerce |
USD 1.0bn |
USD 6.0bn |
Personalization, agentic commerce, search, inventory
optimization and service automation. |
|
Energy and utilities |
USD 0.8bn |
USD 4.9bn |
Grid forecasting, load balancing, renewables integration
and industrial decarbonization. |
|
Advertising and media |
USD 0.6bn |
USD 4.5bn |
Creative production, personalization, measurement and
multilingual content operations. |
|
Public sector and education |
USD 0.6bn |
USD 4.1bn |
Case handling, citizen services, procurement, education
support and governance. |
|
Other sectors |
USD 0.5bn |
USD 2.3bn |
Legal, real estate, agriculture, logistics niches and
cross-sector SME deployments. |
Automotive remains the flagship AI vertical, but the
spending mix is shifting from pure autonomous-driving ambition to practical
software-defined vehicle platforms, engineering acceleration, manufacturing
intelligence, supply-chain visibility and in-cabin personalization. AI will
also support the EV transition through battery management, charging
optimization and factory efficiency.
10.2
Manufacturing and Industrie 4.0
Manufacturing is the most strategically German AI vertical.
The strongest opportunities are quality control, predictive maintenance,
process optimization, energy efficiency, robotics, worker assistance and
digital twins. The market favors vendors that understand machines, production
data and shop-floor constraints rather than generic AI providers.
10.3
BFSI
Banks and insurers are adopting AI for fraud, risk,
compliance, claims, customer support and advisory. The market is attractive but
regulated. Explainability, bias management, model risk governance and
auditability are non-negotiable, particularly for credit, insurance pricing, HR
and customer-impacting automated decisions.
10.4
Healthcare and life sciences
Healthcare AI has strong long-term upside due to medical
imaging, clinical documentation, hospital workflow automation, drug discovery
and patient operations. Adoption depends on clinical validation, CE marking
where applicable, MDR alignment, cybersecurity and privacy-preserving
architectures such as federated learning.
10.5
Retail, e-commerce and media
Retail and media are becoming GenAI laboratories:
personalization, search, dynamic content, product data enrichment, customer
service and agentic commerce. The challenge is that consumer-facing AI requires
brand safety, accuracy, data portability and resilience against AI search
disruption.
10.6
Energy, utilities and public sector
Energy AI is driven by grid complexity, renewable
integration, demand forecasting, maintenance, asset management and
decarbonization. Public-sector AI will grow more slowly but can become
significant through document handling, citizen services, procurement,
education, internal search and case management.
11.
Competitive Landscape and Startup Ecosystem
Germany’s competitive landscape is a three-layer structure:
global hyperscalers and enterprise software platforms; German and European
industrial, cloud and applied-AI players; and a fast-growing startup ecosystem
focused on B2B solutions. The 2026 market rewards partnerships more than
isolation. Large customers often want a mix of global model capability,
German/EU deployment control and domain-specific implementation.
|
Competitive
group |
Examples
/ role |
Strategic
position |
|
Global AI platforms |
Microsoft, OpenAI ecosystem, Google, AWS, NVIDIA, IBM,
Salesforce, Oracle |
Provide foundation models, cloud AI, GPUs, copilots and
developer platforms. |
|
German enterprise and industrial champions |
SAP, Siemens, Bosch, Deutsche Telekom/T-Systems, Siemens
Healthineers, Infineon |
Control distribution into enterprise, industrial,
healthcare, telecom and infrastructure markets. |
|
European AI and cloud players |
Mistral, DeepL, OVHcloud, Aleph Alpha/Cohere alliance,
Schwarz Group cloud assets |
Compete on language, sovereignty, enterprise security and
regional trust. |
|
Startups and scaleups |
Parloa, Black Forest Labs, n8n, Celonis-adjacent process
AI, DeepL, healthcare and industrial AI startups |
Specialize in B2B workflows, automation, vertical data and
fast productization. |
|
Consulting and integrators |
Accenture, Capgemini, IBM Consulting, SAP services,
T-Systems, PwC, KPMG, Deloitte, local Mittelstand consultancies |
Convert AI intent into production systems, governance and
operating models. |
·
The German AI Startup
Landscape 2025 counts 935 AI startups, up 36% year on year, with more than 90%
survival among AI-focused startups listed.
·
Berlin and Munich remain
the dominant hubs, but Hamburg, Karlsruhe, Stuttgart, Cologne, Darmstadt,
Aachen, Düsseldorf and Frankfurt are part of a broader AI geography.
·
Parloa’s January 2026
funding round and USD 3 billion valuation illustrates investor appetite for AI
customer-service automation.
·
The Cohere-Aleph Alpha deal
highlights a key 2026 trend: sovereign AI does not always mean purely national
AI. It can mean trusted alliances, secure deployments and regulated-market
focus.
·
Bitkom’s 2026 unicorn
overview shows AI companies among Germany’s newest billion-euro technology
firms, reinforcing the concentration of new value creation in AI-heavy
categories.
Competitive
outlook to 2035
By 2035, Germany is unlikely to win by owning every layer of
the AI stack. It can win by controlling the application layer in industries
where it has global domain depth: automotive, machinery, chemicals, healthcare,
energy systems, robotics, enterprise software and regulated services. The
strategic question is therefore not “Can Germany build an OpenAI?” but “Can
Germany build the most trusted and operationally valuable AI systems for
real-economy industries?”
12.
Opportunities, Risks and Strategic Recommendations
12.1
Strategic opportunities
·
Industrial AI
platformization: repeatable AI modules for maintenance, quality, energy,
production planning and worker assistance.
·
AI governance and
compliance tooling: AI Act readiness, model inventories, risk classification,
audits and documentation automation.
·
German-language enterprise
AI: domain-specific copilots for legal, healthcare, finance, manufacturing and
public administration.
·
Sovereign and hybrid AI
deployment: data residency, controlled inference, private models, local RAG and
sector-specific security.
·
AI services for SMEs:
packaged adoption programs with fixed scope, predictable pricing and fast ROI.
·
Healthcare and medical AI:
radiology, diagnostics support, clinical documentation, hospital operations and
life-science research.
·
Energy and sustainability
AI: grid forecasting, emissions analytics, efficiency optimization and
industrial decarbonization.
12.2
Strategic risks
|
Risk |
Why
it matters |
Mitigation |
|
Regulatory friction |
High-risk systems require documentation, oversight and
conformity preparation. |
Build AI governance from the start; classify use cases
early. |
|
Data readiness gap |
Poor data quality prevents ROI even when models are strong. |
Create data product owners and improve master data before
scaling. |
|
Compute and energy constraints |
AI workloads require power, cooling, GPUs and reliable
infrastructure. |
Use hybrid architectures, efficient inference, edge
deployment and AI Factory access. |
|
Talent shortage |
AI teams need data, engineering, domain and compliance
skills. |
Train domain staff, use managed services and standardize
reusable patterns. |
|
Vendor lock-in |
Dependence on one cloud/model provider can limit
negotiation and resilience. |
Adopt model-agnostic architecture where possible and
separate data layer from model layer. |
|
Trust failure |
Bad outputs, bias, hallucination or security incidents can
damage adoption. |
Use human oversight, testing, red-teaming, monitoring and
clear escalation. |
|
Stakeholder |
Recommended
action |
|
AI vendors |
Sell outcomes and compliance together. Provide
German-language reliability, audit trails, risk classification and
integration templates. |
|
Consultants / integrators |
Build repeatable industry packages rather than only hourly
advisory. AI governance, MLOps and data readiness are major demand pools. |
|
Investors |
Prioritize B2B AI with defensible domain data,
regulated-sector credibility, workflow ownership and measurable ROI. |
|
SMEs |
Start with one painful workflow, one measurable KPI and one
controlled AI deployment. Avoid broad platform projects too early. |
|
Large enterprises |
Create an AI portfolio office that tracks value, risk,
reuse, governance and model/vendor dependencies. |
|
Policymakers |
Treat compute, data spaces, AI literacy, procurement
clarity and SME enablement as one integrated competitiveness agenda. |
13.
90-Day Action Plan
The following 90-day plan converts the report into action
for a company, startup, consulting team or publisher that wants to build a
Germany AI market strategy.
|
Timeline |
Action |
Output |
|
Days 1-15 |
Create AI use-case inventory across operations, customer
service, finance, sales, HR, legal and IT. |
Prioritized list of 10-20 AI opportunities with owners. |
|
Days 16-30 |
Classify each use case by data sensitivity, AI Act risk
category, business value and implementation difficulty. |
AI portfolio map: quick wins, regulated bets, strategic
investments and avoid list. |
|
Days 31-45 |
Choose 2 quick-win pilots and 1 strategic pilot. Define
KPI, baseline, guardrails and human oversight. |
Pilot charter with ROI logic and risk controls. |
|
Days 46-60 |
Prepare data, vendor shortlist, integration plan and AI
governance checklist. |
Implementation blueprint and procurement criteria. |
|
Days 61-75 |
Run controlled pilot with logging, human review,
model-output testing and user feedback. |
Pilot performance report and risk findings. |
|
Days 76-90 |
Decide scale/no-scale, document lessons, create training
material and prepare production architecture. |
Production recommendation and 6-month AI roadmap. |
·
Named owner for each AI
system.
·
Business purpose and
prohibited-use screening.
·
Data sources, retention and
processing location documented.
·
Model/provider/version
recorded in an AI system inventory.
·
Human oversight and
escalation path defined.
·
Accuracy, bias, security
and hallucination tests performed before production.
·
Monitoring, incident
response and update process established.
·
Staff AI literacy training
completed for users and supervisors.
14.
Methodology and Source Notes
Methodology
This article was built through a structured refresh process:
the uploaded 2024 report of Narrativa - AI was used as the baseline structure and original
forecast; current sources were reviewed for 2025-2026 adoption, market size,
regulatory and infrastructure changes; then forecasts and segment assumptions
were revised using a top-down market-sizing model and qualitative adjustment
factors.
|
Model
input |
Use
in this ebook |
|
Uploaded 2024 report |
Baseline segmentation, 2024 market value, original 2035
forecast and chapter architecture. |
|
Public market anchors |
GTAI 2025/2026 AI market figures and public adoption data
were used to recalibrate 2026-2031 trajectory. |
|
Adoption surveys |
ifo and Bitkom data were used to update enterprise adoption
and SME/microbusiness assumptions. |
|
Regulatory sources |
European Commission AI Act timelines were used to update
compliance risk and high-risk deployment timing. |
|
Infrastructure sources |
Reuters, EuroHPC, European Commission and Jülich sources
were used to update data-center, AI Factory and compute capacity sections. |
|
Startup and deal flow |
appliedAI, Bitkom and Reuters sources were used to update
startup scale, venture momentum and consolidation. |
1. Client source. Original
uploaded report: Germany Artificial Intelligence (AI) Market Size, Share and
Trends Analysis Report, published 2024, forecast period 2024-2035.
2. European Commission. AI
Act implementation timeline, Shaping Europe’s Digital Future. Accessed 8 July
2026. https://digital-strategy.ec.europa.eu/en/policies/regulatory-framework-ai
3. ifo Institute. More
Than Half of Companies in Germany Use Artificial Intelligence, May 2026 survey.
Accessed 8 July 2026.
https://www.ifo.de/en/facts/2026-06-05/more-half-companies-germany-use-artificial-intelligence
4. Germany Trade and Invest.
Artificial Intelligence in Germany, Fact Sheet 2025/2026. Accessed 8 July
2026.
https://www.gtai.de/en/invest/industries/digital-economy/artificial-intelligence
5. appliedAI Institute for
Europe. German AI Startup Landscape 2025. Accessed 8 July 2026.
https://www.appliedai-institute.de/en/publications/ai-startup-landscape-2025/
6. Reuters. Germany
seeks doubling of AI data centres by 2030, 17 March 2026. Accessed 8 July 2026.
https://www.reuters.com/sustainability/climate-energy/germany-seeks-doubling-ai-data-centres-by-2030-2026-03-17/
7. European Commission. AI
Factories and InvestAI Facility. Accessed 8 July 2026.
https://digital-strategy.ec.europa.eu/en/policies/ai-factories
8. EuroHPC Joint
Undertaking. Germany - JUPITER AI Factory. Accessed 8 July 2026.
https://www.eurohpc-ju.europa.eu/ai-factories/germany_en
9. Forschungszentrum Jülich.
JUPITER - Exascale for Europe. Accessed 8 July 2026.
https://www.fz-juelich.de/en/jsc/jupiter
10. Bitkom. Breakthrough
in Artificial Intelligence, September 2025. Accessed 8 July 2026.
https://www.bitkom.org/Presse/Presseinformation/Durchbruch-Kuenstliche-Intelligenz
11. Bitkom. Digital
transformation of industry, April 2026. Accessed 8 July 2026. https://www.bitkom.org/Presse/Presseinformation/Humanoide-Roboter-KI-digitale-Transformation-Industrie
12. Reuters. Germany
plans AI offensive to catch up on key technologies, 15 July 2025. Accessed 8
July 2026. https://www.reuters.com/technology/germany-plans-ai-offensive-catch-up-key-technologies-document-shows-2025-07-15/
13. Reuters. German AI
startup Parloa triples valuation to $3 billion, 15 January 2026. Accessed 8
July 2026.
https://www.reuters.com/business/german-ai-startup-parloa-triples-valuation-3-billion-latest-fundraise-2026-01-15/
14. Reuters. Cohere buys
Germany’s Aleph Alpha to expand in Europe, 24 April 2026. Accessed 8 July 2026.
https://www.reuters.com/legal/transactional/canadas-cohere-germanys-aleph-alpha-announce-merger-handelsblatt-reports-2026-04-24/
15. Bitkom. Unicorns in
Germany, 2026. Accessed 8 July 2026.
https://www.bitkom.org/Themen/Startups-Scaleups/Unicorns-in-Deutschland
Closing note
Germany’s AI market is entering a decisive phase. The
opportunity is not merely to use AI tools; it is to operationalize trustworthy
intelligence in the real economy. The country’s best path to leadership is to
pair industrial depth with compliant, secure, multilingual, explainable and
measurable AI systems. The next winners will be those who can convert AI from a
technology headline into durable productivity, customer value, resilience and
export competitiveness.
Discussion
Comments
Approved comments are published after moderation to keep discussion useful and spam-free.
No comments yet. Start the discussion below.