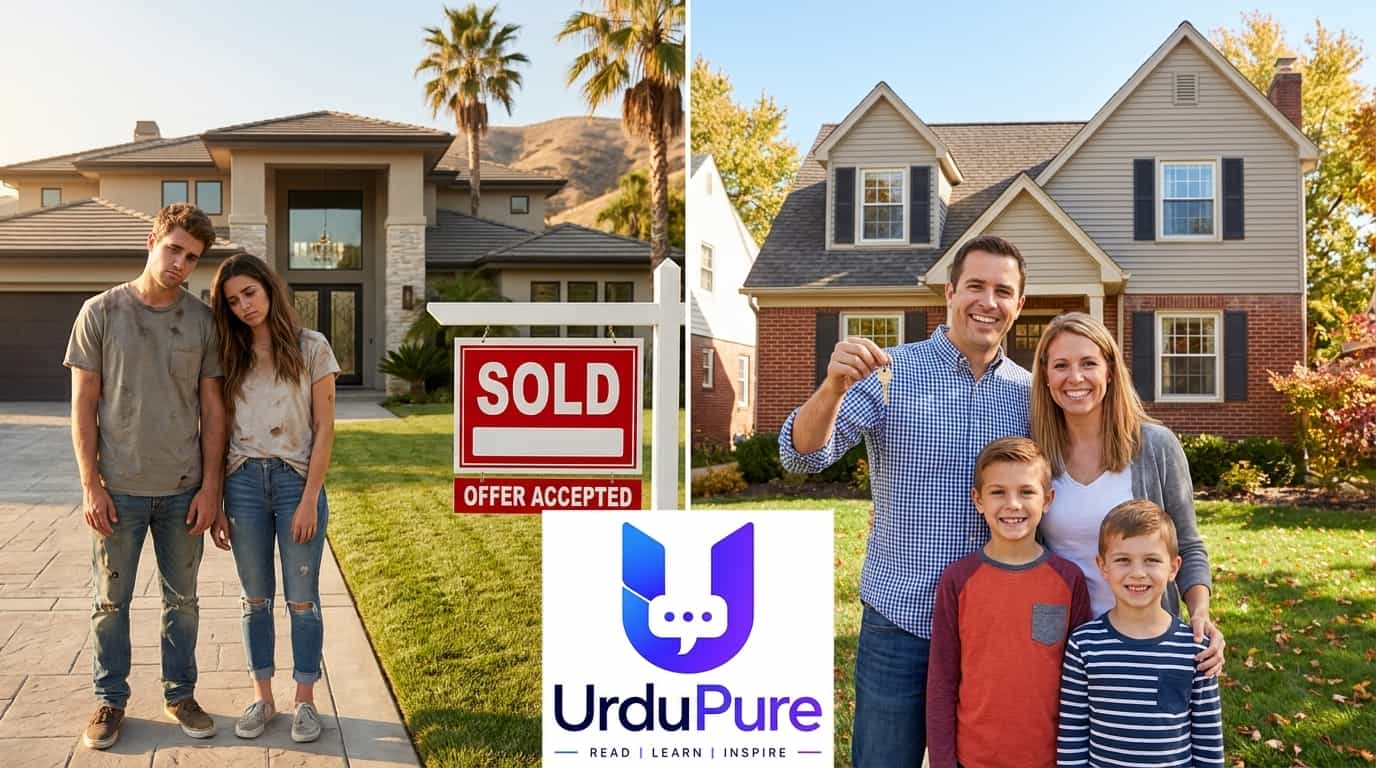
The American Dream Has a New Price Tag — And a New Zip Code
Somewhere in America right now, a young couple is sitting on a couch they don't own, in an apartment they're renting, looking at a housing market that has not meaningfully invited them in since 2021 — when mortgage rates were near historic lows and their student loans still felt like a distant abstraction.
They are not imagining the difficulty. The numbers are real. The median listing price of an existing U.S. home hit $399,900 in January 2026 — essentially the psychological threshold of $400,000 — down just 0.1% from the year before. Mortgage rates, which briefly touched a hopeful 5.98% in late February 2026, climbed back to 6.30% by mid-April. Every tenth of a percentage point on a $400,000 mortgage is the difference between a payment you can manage and one that you cannot.
This is the 2026 housing market. Worse than the 1980s affordability crisis by some measures. Better than the absolute peak of 2023 by others. And for the generation most directly affected — millennials in their mid-30s and Gen Z in their late 20s — an exercise in patience that is starting to feel permanent.
But the full story is more complicated than the headline. Because somewhere else in America, in cities with names that don't end in "Angeles" or "Francisco" or "Boston," buyers are finding something that has almost vanished from the coastal imagination: affordable housing in an economy with real jobs.
The American Dream has not died. It has moved to Ohio.
How Bad Is It, Actually? The Honest Affordability Picture
Let's establish the baseline before offering any comfort, because the baseline deserves to be taken seriously.
The 30-year fixed mortgage rate: Freddie Mac's survey placed it at 5.98% in late February 2026 — the first time it had dropped below 6% in years, a psychological milestone that generated enormous optimism. It didn't last. By April 16, the rate was back to 6.30%. The Mortgage Bankers Association projects rates will remain between 6% and 6.5% through 2026. Redfin's forecast calls for an average of 6.3% for the full year.
The monthly payment math: At 6.3% on a $399,900 home with a 20% down payment (a $79,980 upfront investment that a majority of first-time buyers cannot produce), the monthly principal and interest payment is approximately $1,987. Add property taxes, homeowner's insurance, and PMI if the down payment is less than 20%, and the real monthly cost of a median-priced home exceeds $2,500 in most markets.
The standard financial guideline suggests spending no more than 28–30% of gross income on housing. That means the median American home requires a household income of roughly $107,000–$115,000 just to hit the 30% affordability threshold — a salary that is above the U.S. median for individual earners and barely within reach for many two-income households.
The affordability threshold: Realtor.com's chief economist Danielle Hale noted that 2026 should be the first year since 2022 that the typical mortgage payment share of income drops below 30% — but only barely. "Improving affordability is a really important component of that increase in home sales for 2026," Hale said. The operative word is "improving." Not "improved." Not "solved."
The Lock-In Effect: The Problem Inside the Problem
The housing market's most misunderstood structural headwind has a name that sounds like an economics term but is actually a human story at massive scale: the mortgage lock-in effect.
Here is how it works. Between 2020 and 2022, roughly 14 million American homeowners refinanced their mortgages at historic lows — many below 3%, some below 2.5%. These homeowners are now, effectively, trapped in their homes by their own good fortune. Selling means surrendering a 2.75% mortgage to buy a new home at 6.3% — more than doubling the interest cost on a similar loan. For most homeowners, the math makes selling irrational regardless of their desire to move.
The result: inventory is constrained not because people don't want to sell, but because selling is economically self-destructive for anyone who refinanced in the pandemic era. The NAHB noted a milestone: the share of mortgages with rates greater than 6% finally exceeded the share below 3% in early 2026. But "roughly 80% of mortgages" still have rates at 6% or lower — meaning the lock-in effect will constrain supply for years.
This is why the 2026 housing market feels so stuck despite falling from its 2022 peak. Prices aren't collapsing because the people who own homes rationally refuse to sell. First-time buyers can't enter because the existing owners won't leave. And the entire market calcifies.
What the Data Actually Shows: The Forecasts
The major housing economics institutions have produced forecasts for 2026 that are simultaneously more optimistic than the lived experience of first-time buyers and more honest than the "housing is recovering" narratives in mainstream financial media.
Zillow: Home values will grow 1.2% in 2026 after staying roughly flat in 2025. The number of major markets seeing annual price declines will drop from 24 to approximately 12. Mortgage rates will stay above 6% throughout the year.
Redfin: The 30-year fixed rate will average 6.3% for 2026, down from 6.6% in 2025. A weaker labor market will lead the Federal Reserve to cut interest rates, but "lingering inflation risk" will prevent more than modest cuts. Rates may dip below 6% "occasionally, but not for any meaningful period."
Realtor.com: Home prices expected to rise 2.2%, adding to the 2.0% gain in 2025. But because inflation is projected to run faster than that, real (inflation-adjusted) home prices will decline for the second consecutive year — giving buyers breathing room that the nominal numbers don't capture.
NAHB: The median listing price of an existing home was $399,900 in January 2026, down 0.1% year-over-year. New single-family home sales ran at a 587,000 annual pace in January 2026 with 9.7 months of supply — giving builders more reason to offer pricing flexibility and incentives.
The bottom line: The 2026 housing market is improving, slowly and unevenly, in ways that will not feel like relief to the millions of Americans who are one emergency away from not making rent, let alone a mortgage payment.
Gen Z Homeownership: The Flatline Problem
The housing crisis is a generational story, and its most acute chapter is being written by Gen Z — the roughly 67 million Americans born between 1997 and 2012, now aged 14–29, with the oldest cohort squarely in the first-time homebuyer age range.
Redfin's 2026 predictions are blunt: "Gen Z and millennial homeownership rates flatlined last year, and we expect that trend to continue."
This is not a small problem. Homeownership is the primary mechanism through which American households build intergenerational wealth. It is the difference, in most cases, between retirement security and retirement precarity. The decades-long tradition of buying a home in your late 20s, building equity through your 30s and 40s, and entering retirement with a paid-off asset to bequeath or liquidate is being severed in real time for an entire generation.
The barriers are structural. Student loan debt has delayed household formation. The down payment requirement on a $400,000 home (20% = $80,000) is a figure that many young professionals cannot accumulate within the first decade of their working lives, especially in high-cost-of-living markets where rents consume 40–50% of take-home pay.
And the supply side offers no easy answers. Building new homes at scale requires labor, materials, and land — all of which have become more expensive. The NAHB reported that residential building material prices have been growing above 3% annually since June 2025, even as builder confidence (measured by the NAHB/Wells Fargo Housing Market Index at 34 in April 2026) remains "subdued."
Where Buyers Are Actually Winning: The Midwest Alternative
Here is where the story turns. Not cheerfully, not with false comfort, but with specificity — because the national housing narrative consistently obscures the fact that the United States is not one housing market. It is dozens of them.
And in several of those markets, the picture looks entirely different from the coastal crisis narrative.
Columbus, Ohio: Housing economists from the National Association of Realtors identified Columbus as one of the most promising markets for first-time buyers in 2026. It sits close to major universities (Ohio State), has a diversifying tech and healthcare employment base, and has maintained relative affordability compared to coastal markets. Median home prices in Columbus remain well below the national median, and inventory has been improving.
Indianapolis, Indiana: Another Midwest market experiencing what one NAR economist called "outsized growth" — driven by its affordability, proximity to major universities, and growing healthcare and logistics employment base. Indianapolis is a market where a household earning $75,000–$90,000 can realistically pursue homeownership without consuming their entire financial life in the process.
Kansas City, Missouri/Kansas: The bi-state metro sits at the confluence of affordability, economic diversification, and Midwest stability that defines the emerging "second-tier city" opportunity in American housing. Professional transplants from more expensive coastal markets are discovering that Kansas City offers urban amenity alongside genuinely livable housing costs.
The Midwest thesis: Markets like Columbus, Indianapolis, and Kansas City have long been more affordable and are close to major universities — creating employment density, cultural amenity, and the kind of economic stability that makes homeownership a viable proposition for households that would be priced out of the coasts for another decade.
The caveat: these markets are not cost-free. Rapid in-migration from coastal markets has already begun to push prices upward. The window of maximum affordability may be closing even in the Midwest's best markets. The buyers who act in 2026 are buying into markets that may look significantly more expensive by 2030.
Practical Guidance: What to Do If You're a First-Time Buyer in 2026
The housing market does not wait for the perfect moment. Here is what the evidence suggests for buyers navigating 2026:
1. Consider adjustable-rate mortgages (ARMs) strategically. ARMs offer lower initial rates — sometimes 50–75 basis points below the 30-year fixed rate — in exchange for rate variability after an initial fixed period (typically 5 or 7 years). If you expect to move within 7 years or believe fixed rates will fall significantly, an ARM may make mathematical sense. Understand the risk fully before committing.
2. Look at new construction. Builders are offering pricing flexibility and financing incentives in 2026 that the existing-home market is not — because builders need to move inventory and can negotiate in ways that private sellers cannot. New-home sales at the current pace give builders meaningful motivation to deal.
3. Take the Midwest seriously. If your career can accommodate geographic flexibility, Columbus, Indianapolis, and Kansas City offer the most realistic path to first-time homeownership for household incomes in the $70,000–$100,000 range in 2026.
4. Build your down payment aggressively. Rates above 6% make the down payment question critical — every additional dollar down reduces the principal on which you pay 6.3% annually. High-yield savings accounts (currently paying 4.5–5%) provide a meaningful return on down payment savings while you wait.
5. Watch the Federal Reserve. The Fed is projected to make two 25 basis point rate cuts in 2026. Each cut may not dramatically move mortgage rates (which are driven by bond markets, not directly by the Fed funds rate), but a pattern of cuts signals a direction — and mortgage rates tend to move in anticipation of that direction.
Patience Is a Strategy, But Not a Permanent One
The 2026 housing market is not a crisis in the acute sense — home values are not collapsing, banks are not failing, and the structural demand for housing remains fundamentally sound. It is a chronic affordability problem that is being slowly addressed through a combination of rising incomes, easing rates, and careful market recalibration.
For the couple on the couch, watching the Zillow app cycle through homes they cannot afford in cities where they cannot afford to live: there is no simple answer. But there are real answers — in the data, in the geography, and in the patience to wait for the moment the market and your finances align.
The American Dream has a new price tag. But it also has a new zip code. And for those willing to find it, it is still there.
home prices 2026, housing market 2026, mortgage rates 2026, is it a good time to buy a house, housing affordability, real estate 2026, Gen Z homeownership, Midwest housing, Zillow forecast, Redfin 2026 predictions, housing affordability 2026, 30-year mortgage rate, first-time homebuyers, Gen Z homeownership, Midwest housing market, housing inventory 2026, Zillow forecast 2026, Redfin predictions
Discussion
Comments
Approved comments are published after moderation to keep discussion useful and spam-free.
No comments yet. Start the discussion below.