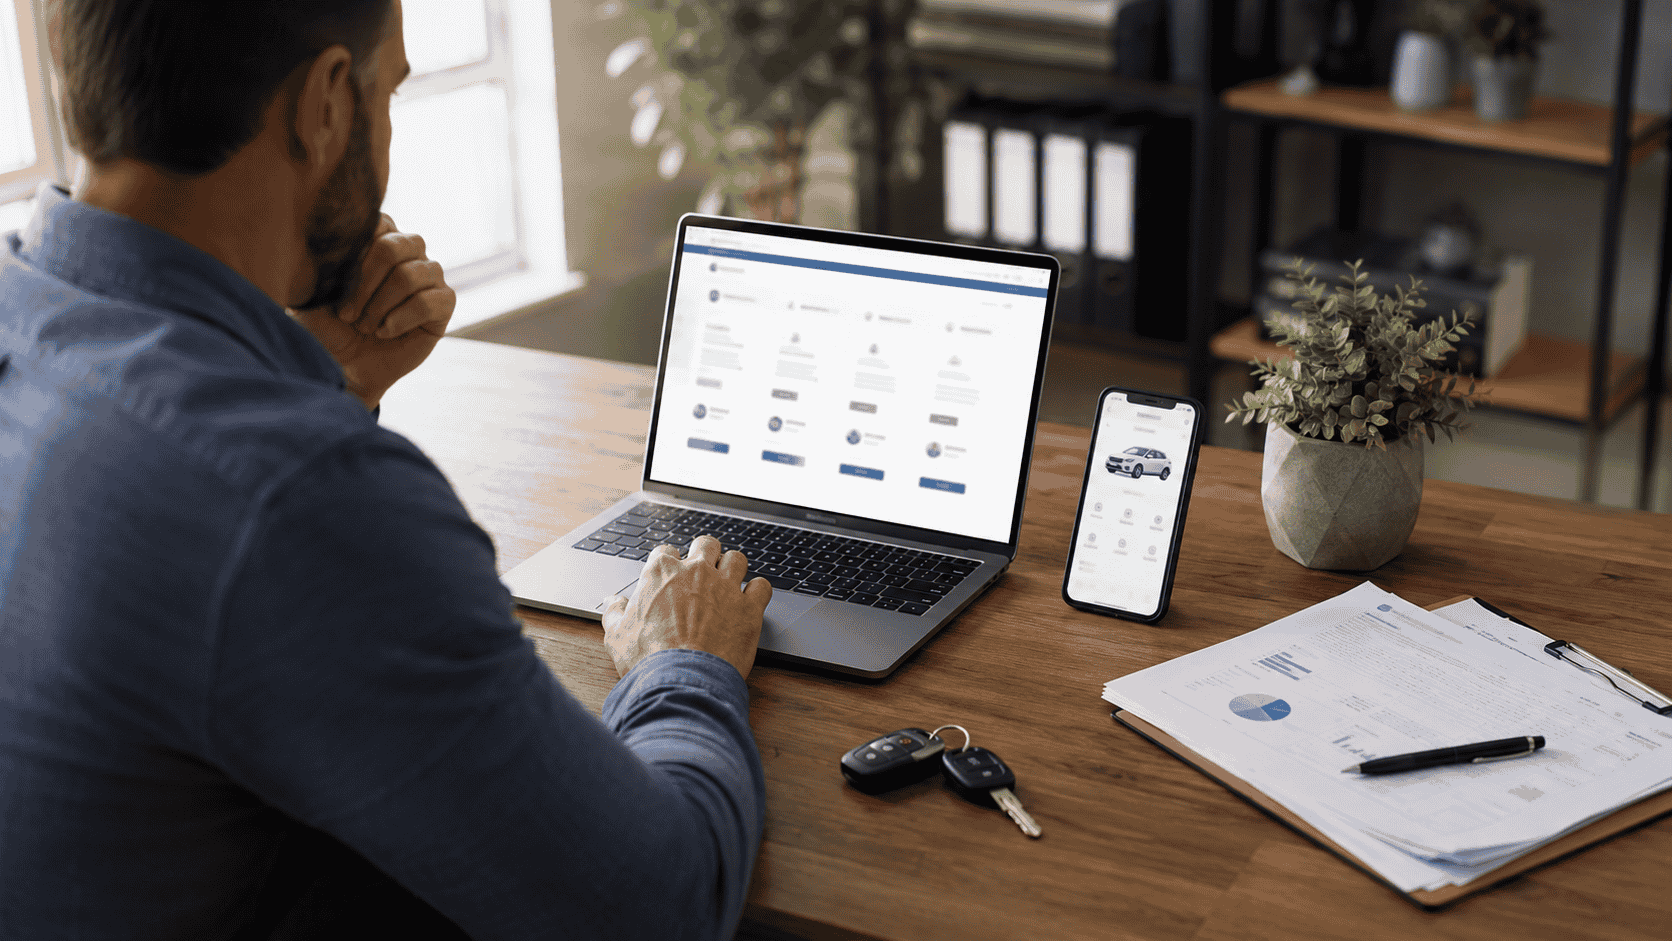
Auto Insurance Quotes: How to Compare Rates and Find the Best Policy in 2026
Auto insurance is one of those bills people often pay without thinking too much about it. The policy renews. The premium goes up. You feel annoyed for a few minutes. Then you pay it anyway. But in 2026, that habit can cost serious money. Auto insurance quotes can vary widely between companies, even for the same driver, same car and same coverage level. That means the first quote you receive is rarely the whole market. It is just one company’s estimate of your risk. If you compare properly, you may find a better price, stronger coverage or useful discounts you were missing. The goal is not simply to find the cheapest auto insurance quote.
The goal is to find the best policy for your real life.
Key Takeaways
Auto insurance quotes are estimates, not always final prices.
The cheapest quote is not always the best policy.
Compare at least three quotes before buying or renewing.
Use the same coverage limits and deductibles when comparing.
Liability, collision and comprehensive coverage protect against different risks.
Your driving record, location, vehicle, mileage and coverage choices can affect your premium.
A higher deductible can lower your premium, but only choose one you can afford.
Review your auto insurance every year or after major life changes.
What Is an Auto Insurance Quote?
An auto insurance quote is an estimated price from an insurance company.
It shows how much you may pay for a policy based on your driver profile, vehicle, location and coverage choices.
A quote usually includes:
Monthly premium
Six-month or annual premium
Liability coverage
Collision coverage
Comprehensive coverage
Deductibles
Optional add-ons
Discounts
Payment terms
But a quote is not always the final price.
The insurer may adjust it after checking your driving record, claims history, credit-based insurance score where allowed, vehicle details and household driver information.
That is why you should treat quotes as estimates until the policy is officially issued.
Why Comparing Auto Insurance Quotes Matters
Many drivers stay with the same insurer for years because switching feels like work.
That can be expensive.
Insurance companies use different pricing models. One company may see you as a low-risk driver. Another may charge more because of your ZIP code, vehicle model or claims history.
The Insurance Information Institute explains that auto insurance pricing can depend on factors such as driving record, how much you use your car, where you live, age, gender where allowed, vehicle type, credit where permitted and coverage choices. (III)
That means your friend’s cheapest insurer may not be cheapest for you.
Your own best quote depends on your personal profile.
Minimum Coverage vs Full Coverage
One of the first decisions is whether you need minimum coverage or full coverage.
Minimum coverage usually means the lowest insurance required by your state or local law.
It is cheaper, but it may offer limited protection.
In many cases, minimum coverage focuses on liability. That means it helps pay for injuries or damage you cause to other people, but it may not repair your own car after an accident.
Full coverage is not a formal legal term.
People usually use it to describe a policy that includes liability coverage plus collision and comprehensive coverage.
Collision coverage helps pay for damage to your car after hitting another vehicle or object. Comprehensive coverage helps pay for damage from non-collision events such as fire, theft or weather. The National Association of Insurance Commissioners also notes that collision and comprehensive coverage often come with deductibles and may be required by lenders for financed or leased vehicles. (NAIC Content)
Minimum coverage may be enough for some drivers with older cars and strong savings.
Full coverage may be better if your car is newer, financed, leased or expensive to repair.
How Much Does Auto Insurance Cost in 2026?
Auto insurance costs vary by driver, state, vehicle and coverage level.
NerdWallet’s June 2026 rate analysis estimated average annual costs of about $2,320 for full coverage and $624 for minimum coverage for drivers with good credit. It also estimated that drivers with poor credit paid much more on average, where credit is allowed in pricing. (NerdWallet)
These numbers are only averages.
Your actual quote may be higher or lower depending on:
Your state
Your city or ZIP code
Your age
Your driving history
Your vehicle
Your annual mileage
Your coverage limits
Your deductible
Your insurer
Your discounts
That is why quote comparison matters more than national averages.
Average prices help you understand the market.
Your own quotes tell you what you may actually pay.
How to Compare Auto Insurance Quotes Correctly
The biggest mistake drivers make is comparing prices without comparing coverage.
A quote that looks cheaper may only be cheaper because it gives you less protection.
To compare properly, use the same details for every quote.
Use the same:
Driver information
Vehicle information
Address
Annual mileage
Liability limits
Collision deductible
Comprehensive deductible
Optional coverages
Policy start date
Payment schedule
Then compare the whole policy, not just the monthly price.
Look at:
Premium
Coverage limits
Deductibles
Exclusions
Discounts
Claims reputation
Customer service
Payment fees
Cancellation rules
Roadside assistance
Rental car reimbursement
Uninsured motorist coverage
A policy that saves $15 per month may not be worth it if it leaves you exposed after an accident.
What Affects Your Auto Insurance Quote?
Auto insurance companies calculate risk in different ways.
Common factors include:
Driving record
Claims history
Age
Location
Vehicle make and model
Vehicle repair cost
Theft risk
Annual mileage
Use of vehicle
Coverage limits
Deductible amount
Credit-based insurance score where allowed
Prior insurance history
Safety features
Discounts
The vehicle itself matters a lot. The Insurance Information Institute says the value of your vehicle, repair cost, theft likelihood, engine size and safety record can all affect the cost to insure it. (III)
This is why you should check insurance quotes before buying a car.
A vehicle may look affordable at the dealership but become expensive when insurance is added.
Step-by-Step Guide to Comparing Auto Insurance Quotes
Step 1: Read Your Current Policy
Start with your current declarations page.
This shows your coverage limits, deductibles, vehicles, drivers and policy dates.
You cannot compare properly if you do not know what you already have.
Step 2: Decide What Coverage You Need
Ask yourself:
Is my car financed or leased?
Could I afford to repair or replace it?
Do I drive every day?
Do I need rental car coverage?
Do I need roadside assistance?
Are my liability limits strong enough?
What deductible can I afford?
Do not let the cheapest quote decide your coverage for you.
Step 3: Get at Least Three Quotes
Compare quotes from different types of providers:
National insurers
Regional insurers
Online insurers
Independent agents
Credit unions or member-based providers
Existing insurer renewal quote
The more quotes you compare, the better your chance of finding a strong deal.
Step 4: Compare Coverage Line by Line
Do not compare one full coverage quote with one minimum coverage quote.
That is not a fair comparison.
Make sure each quote has similar:
Liability limits
Collision coverage
Comprehensive coverage
Deductibles
Optional add-ons
Step 5: Ask About Discounts
Many drivers miss discounts because they do not ask.
Common discounts may include:
Safe driver discount
Multi-car discount
Multi-policy discount
Good student discount
Defensive driving discount
Low mileage discount
Anti-theft device discount
Autopay discount
Paperless billing discount
Paid-in-full discount
Usage-based insurance discount
Discounts vary by insurer, so ask every company separately.
Step 6: Check the Claims Experience
The cheapest company may not feel cheap after a bad claim experience.
Before choosing, check:
Customer reviews
Complaint history where available
Claims satisfaction
Repair network
App experience
Customer support hours
Insurance matters most when something goes wrong.
Step 7: Avoid a Coverage Gap
Do not cancel your old policy until the new one is active.
A lapse in coverage can create legal problems and may make future insurance more expensive.
How to Save Money on Auto Insurance
You can reduce auto insurance costs in practical ways.
Compare Before Every Renewal
Do not renew blindly.
Compare quotes at least once a year, especially if your premium increases.
Raise Your Deductible Carefully
A higher deductible may lower your premium.
But only choose a deductible you can actually pay after an accident.
Bundle Policies
Many insurers offer discounts when you combine auto insurance with home, renters or other policies.
Keep a Clean Driving Record
Tickets, at-fault accidents and serious violations can raise rates.
Safe driving is one of the best long-term savings strategies.
Review Coverage on Older Cars
If your car is older and low-value, collision and comprehensive coverage may become less cost-effective.
But do not drop them unless you can afford the repair or replacement risk.
Ask About Usage-Based Insurance
Some insurers offer programs that track driving behavior or mileage.
These may help safe or low-mileage drivers save money.
Read the rules carefully before enrolling.
Pay in Full if Possible
Some insurers charge fees for monthly payments.
Paying the full policy term upfront may reduce total cost if you can afford it.
Cheap Auto Insurance Is Not Always Good Auto Insurance
Cheap auto insurance can be helpful.
But cheap is not always smart.
A weak policy may leave you exposed after:
A serious crash
A lawsuit
Theft
Storm damage
Hit-and-run damage
Medical expenses
Expensive repairs
Damage to a financed car
If your liability limits are too low, you may be personally responsible for costs above your policy limit.
That is why the right policy matters more than the lowest quote.
The best auto insurance quote gives you a fair price and enough protection for your risk.
When Minimum Coverage May Make Sense
Minimum coverage may make sense if:
Your car is old
Your car has low market value
You rarely drive
You have emergency savings
You own the car outright
You only need legal compliance
You understand the financial risk
But minimum coverage can be risky if:
Your car is financed
Your car is leased
You drive daily
You cannot afford major repairs
You have assets to protect
You live in a high-risk area
You would struggle to replace your car
Minimum coverage is cheaper because it protects less.
That is the trade-off.
When Full Coverage May Be Worth It
Full coverage may be worth it if:
Your vehicle is new
Your car is financed
Your car is leased
Your vehicle is expensive to repair
You rely on your car for work
You cannot afford to replace the vehicle
You want stronger financial protection
You live in an area with theft, storms or animal risk
Full coverage costs more upfront, but it can prevent a bigger financial hit later.
Mistakes to Avoid When Comparing Auto Insurance Quotes
Avoid these common mistakes:
Comparing different coverage levels
Choosing only by monthly premium
Ignoring deductibles
Ignoring liability limits
Forgetting uninsured motorist coverage
Not asking about discounts
Skipping claims reputation
Letting coverage lapse
Dropping full coverage without checking vehicle value
Buying state minimum coverage without understanding the risk
The cheapest quote may look good today.
The wrong policy can hurt badly after an accident.
Myth vs Fact
Myth: All auto insurance companies charge about the same.
Fact: Insurers use different pricing models, so quotes can vary widely.
Myth: The cheapest quote is always best.
Fact: A cheap quote may have lower limits, higher deductibles or weaker protection.
Myth: Minimum coverage protects your own car.
Fact: Minimum coverage often focuses on liability and may not repair your own vehicle after an at-fault crash.
Myth: Full coverage means everything is covered.
Fact: Full coverage still has deductibles, exclusions and limits.
Myth: You only need to compare quotes when buying a new car.
Fact: You should compare quotes at renewal and after major life changes.
Final Thought
Auto insurance is easy to ignore until the day you need it.
Then every detail matters.
The deductible matters.
The liability limit matters.
The exclusions matter.
The claims process matters.
The company you chose because it was slightly cheaper may become the company deciding how quickly your car gets repaired.
So compare carefully.
Ask questions.
Read the policy.
Look beyond the monthly price.
The cheapest auto insurance quote can save money today.
The right auto insurance policy can protect your future.
Frequently Asked Questions
What are auto insurance quotes?
Auto insurance quotes are estimated prices from insurers based on your driver profile, vehicle, location and coverage choices.
How many auto insurance quotes should I compare?
Compare at least three quotes before buying or renewing. More quotes can help you see whether your current insurer is still competitive.
Is auto insurance the same as car insurance?
Yes. In everyday use, auto insurance and car insurance usually mean the same thing.
What is the average cost of auto insurance in 2026?
NerdWallet’s June 2026 analysis estimated average annual costs of about $2,320 for full coverage and $624 for minimum coverage for drivers with good credit, though actual rates vary widely. (NerdWallet)
What is full coverage auto insurance?
Full coverage usually means liability insurance plus collision and comprehensive coverage. It is not a formal legal term and still has limits and exclusions.
What is minimum coverage auto insurance?
Minimum coverage is the lowest level of insurance required by your state or local law. It is cheaper but may provide limited protection.
Does my vehicle affect my insurance quote?
Yes. Vehicle value, repair cost, theft risk, engine size and safety record can all affect premiums. (III)
How can I lower my auto insurance premium?
Compare quotes, raise deductibles carefully, bundle policies, ask about discounts, drive safely, review older-car coverage and avoid coverage gaps.
Should I choose the cheapest auto insurance quote?
Not always. Choose the policy that gives the best balance of price, coverage, deductible, claims support and financial protection.
Is this insurance advice?
No. This article is for general information only. Auto insurance rules vary by location, so check your local requirements and speak with a licensed insurance professional before buying coverage.
auto insurance quotes, car insurance quotes, cheap auto insurance, compare auto insurance, auto insurance rates, best auto insurance companies, full coverage auto insurance, minimum coverage auto insurance, liability insurance, collision coverage, comprehensive coverage, insurance premium, auto insurance discounts, car insurance policy, deductible, vehicle insurance, insurance quote comparison, Auto Insurance, Car Insurance, Insurance Quotes, Personal Finance, Cheap Insurance, Full Coverage, Minimum Coverage, Save Money, Insurance Guide
External Sources
National Association of Insurance Commissioners auto insurance guide
Insurance Information Institute auto insurance pricing factors
NerdWallet auto insurance cost analysis
State insurance department resources
Consumer complaint databases where available
Discussion
Comments
Approved comments are published after moderation to keep discussion useful and spam-free.
No comments yet. Start the discussion below.